Neobanc Pays 1% on Rent. What's the Catch?
Neobanc pays me 1% on my rent for sending it an e-Transfer. On $2,500 a month that is $300 a year, with no credit card and no fee. Here is how it works, where the money sits, and where it can go wrong.
I found it while working out what to do when the Scotia Momentum stops paying 4% on rent. Every rent service I knew charged a fee to put rent on a card and paid nothing of its own. This one is the other way around: the free route is the one that pays. That is unusual enough to deserve its own fine print, so this is the structure, the fees, the two reward tiers, the risks, and the way I am using it.
The whole post in one picture. The numbers are real and the receipts are below.
Neobanc is a wallet that pays your landlord for you
You do not pay your landlord. You fund a Neobanc wallet, and on your rent due date Neobanc sends your landlord an Interac e-Transfer for the full amount. The landlord signs up for nothing and sees a normal e-Transfer, except the sender's name is Neobanc's, not yours. Both of you get a confirmation.
The wallet has to be funded at least three business days before rent is due, with a 3:30 pm Eastern cutoff, or it counts as the next day. Neobanc's terms say the timing is your responsibility, that they do not guarantee a delivery date, and that any late fee from your landlord is yours. In practice the reviewers who are happy give it ten days.
Interac is free. A credit card costs 1.5% or 2.25%
Funding the wallet by Interac e-Transfer costs nothing. Funding it by credit card, Visa, Mastercard or Amex, costs 1.50% on the 1% reward tier or 2.25% on the 2% tier. Neobanc's FAQ says there are no hidden fees, and I found none for a Canadian card. The terms add two things: a one-cent pre-authorization to verify the card, and an extra 1.5% to 3.5% for foreign-currency or international cards.
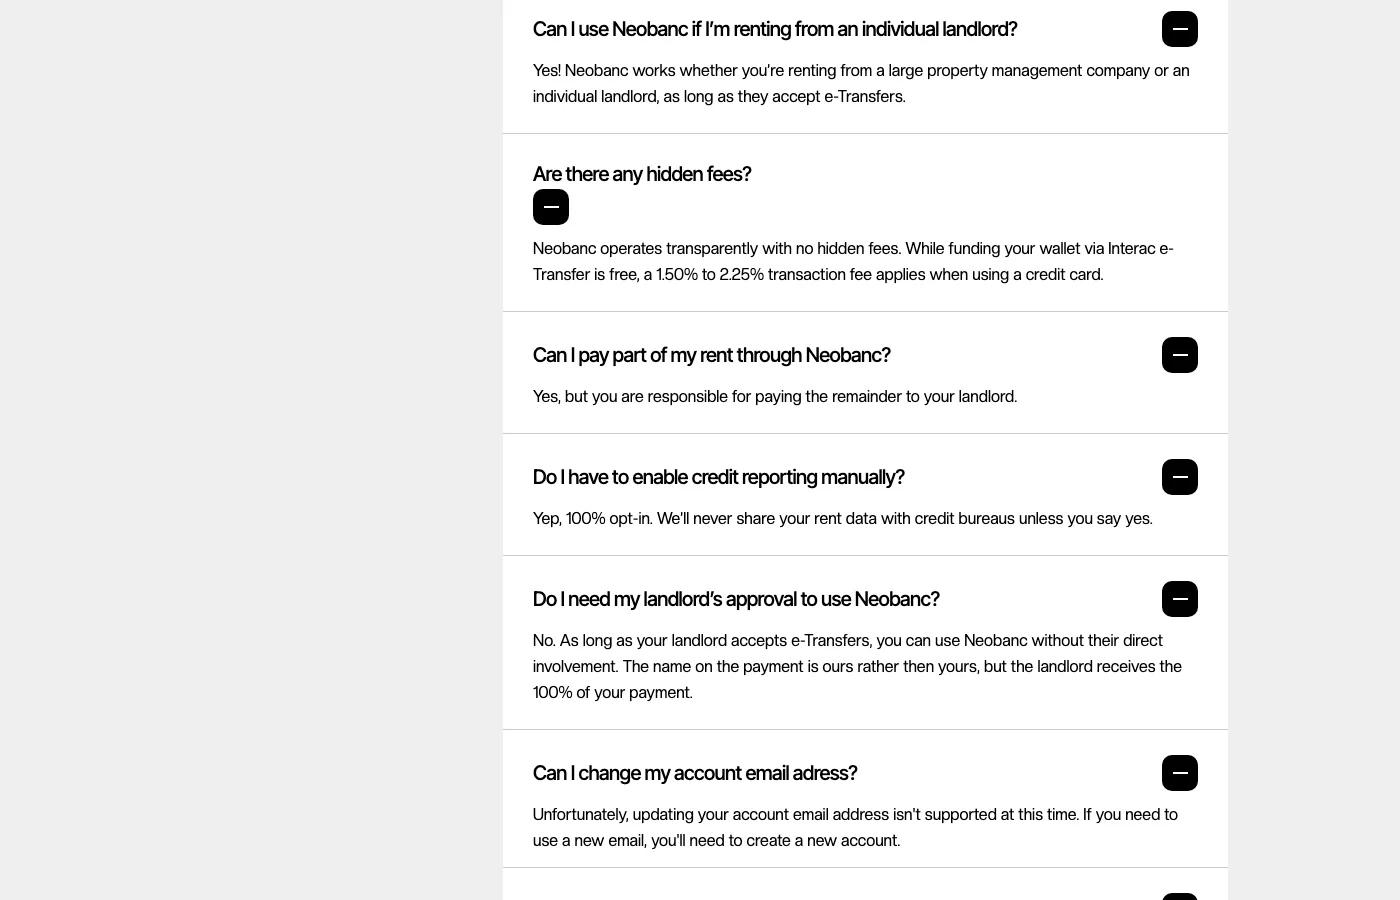
neobanc.com, September 26, 2026. Free by Interac, 1.50% to 2.25% by card. Two answers down: the name on the payment is Neobanc's, not yours.
The reward is store credit, in two tiers
The reward is not cash. Neobanc calls it Credits: non-cash, non-transferable, and usable only toward rent or other bills paid through Neobanc. You pick a tier when you set up the rent, and the FAQ says the choice is fixed for now.
- 1% monthly. Each rent payment earns a credit worth 1% of it, $25 on my rent, usable from the start of the next month's cycle. Next month I fund $2,475 instead of $2,500.
- 2% six-month. Each payment earns 2%, $50 on my rent, but each credit is held for 183 days. April's rent unlocks in October, May's in November. Nothing appears for the first six months, and the terms call it a limited-time promotion for a limited number of customers. Neobanc's own explanation is candid: keeping six months of would-be cash back shortens its payback and keeps you from leaving.
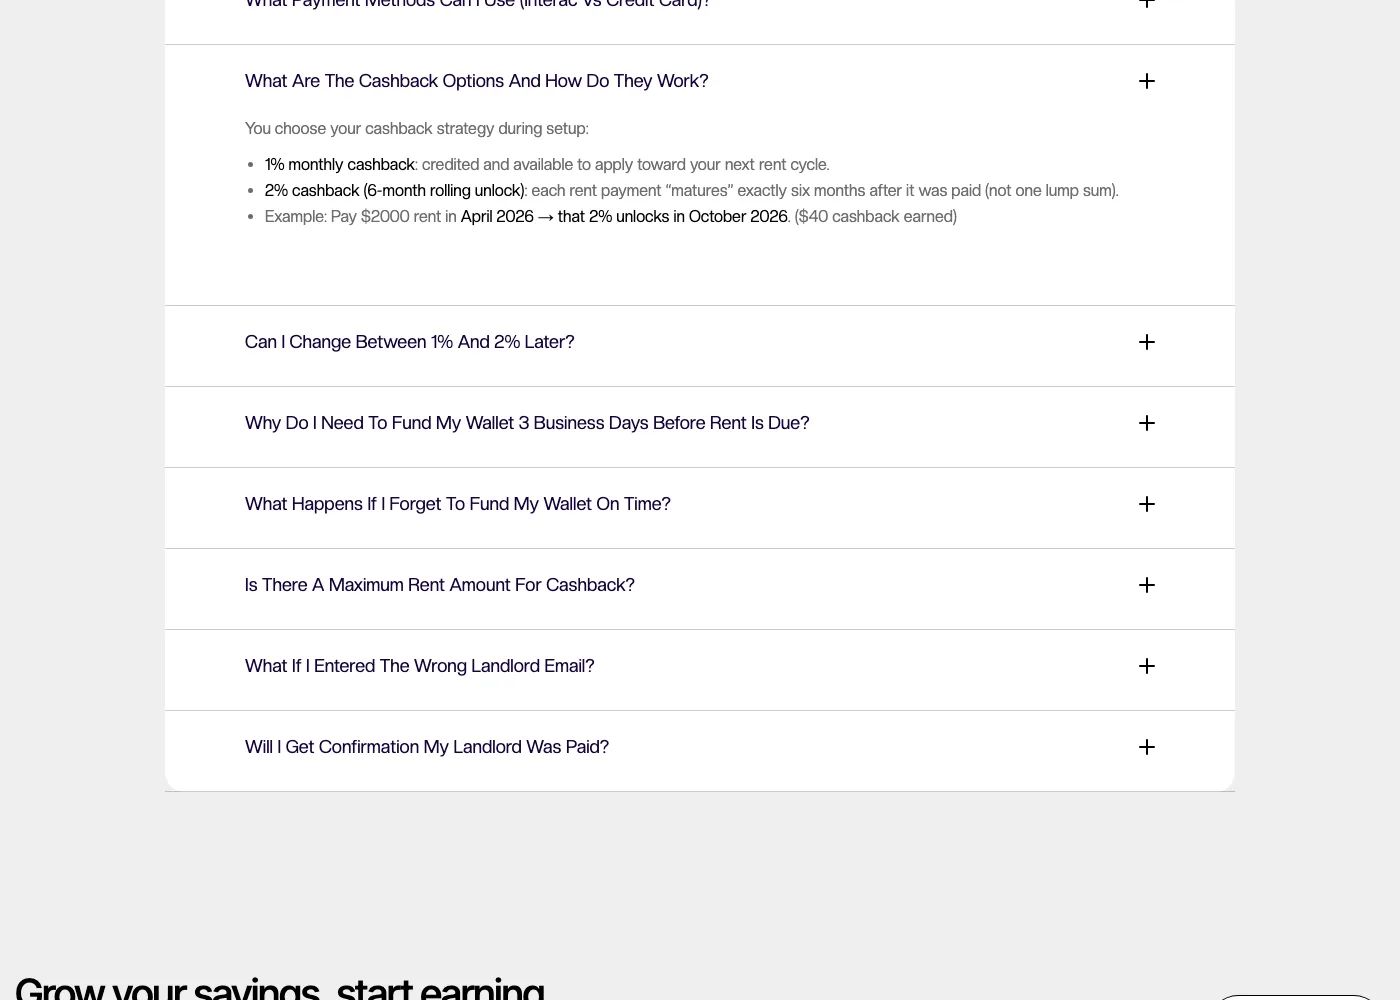
neobanc.com, September 26, 2026. Two tiers, chosen at setup. The example line is the one to read: April's rent unlocks in October.
On the free Interac route the 2% tier is worth an extra $300 a year on my rent, half of it arriving in year two and only if I am still paying through Neobanc. On a card the gap shrinks to $75, because the fee rises by 0.75% to buy an extra 1% of credit. Either way the credit is forfeited for any month you fund late. I take the 1% and the money now.
A credit card adds half a percent, and a question
Put a 2% card in front of the wallet and the math is 2% from the card, plus 1% from Neobanc, minus 1.5% to Neobanc: +1.5% instead of +1%. On my rent that is $150 a year more, $12.50 a month, for putting $2,500 a month through a card.
The question is how that charge posts. Neobanc's terms say a card payment "may incur interest, cash-advance, or other fees imposed by your card issuer," that Neobanc does not control or reimburse them, and that you should check with your issuer whether the transaction is treated as a purchase or a cash advance. A cash advance earns no rewards and starts charging interest the same day. Neobanc's marketing says the TD Cash Back card pays 3% on rent through it and Tangerine pays 2%, but Neobanc never says how the charge is coded, and I could not find a cardholder statement confirming it. Chexy, by contrast, commits in its own notice to the cards that earn their recurring rate through it.
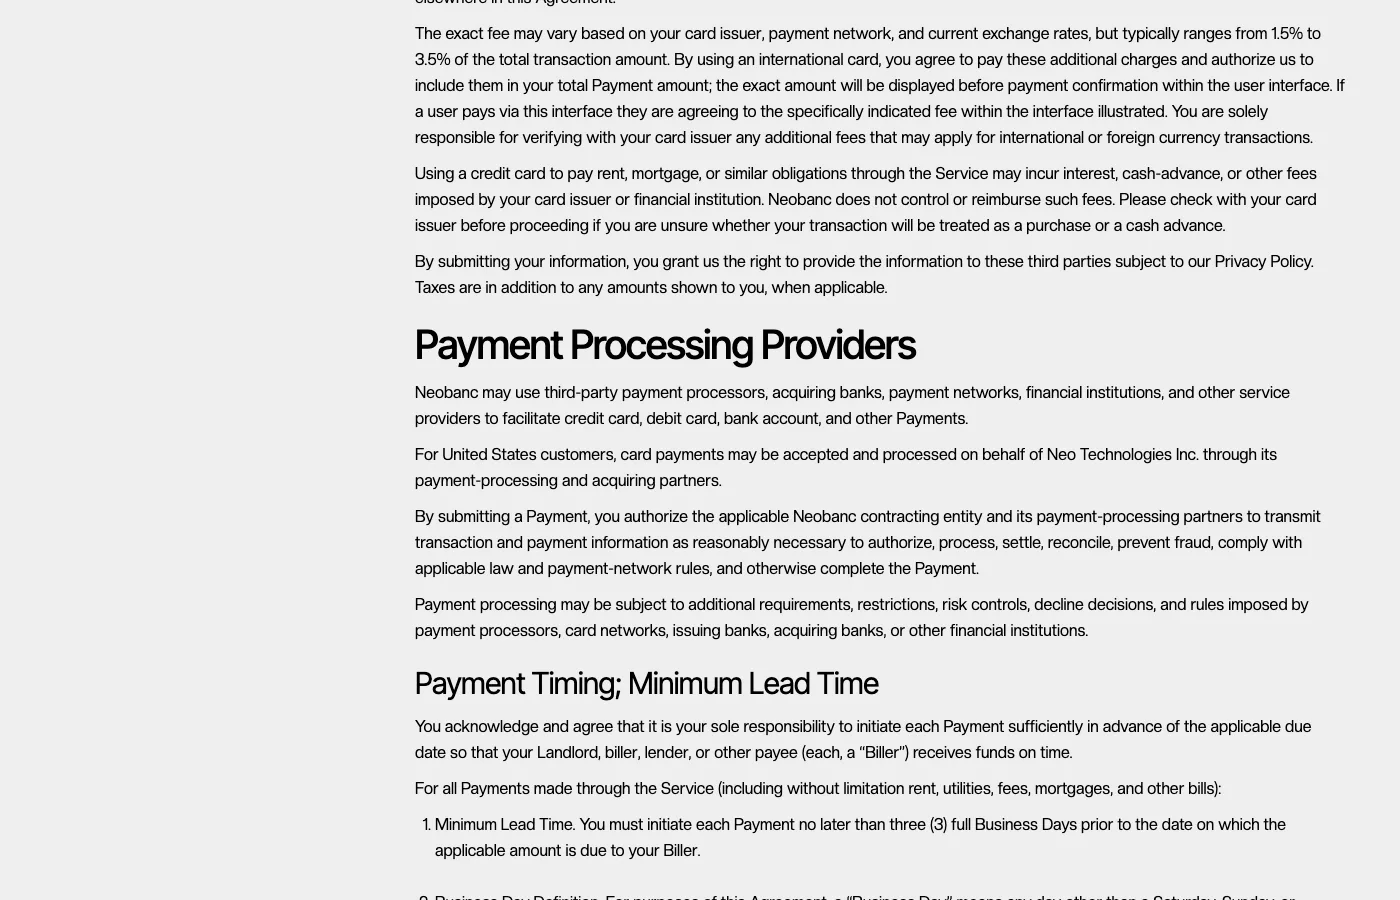
neobanc.com terms of use, September 26, 2026. The paragraph that decides whether a card belongs in front of this wallet. Neobanc puts the question back on you.
So if you want the extra $150: run one month's rent, wait for the statement, and check two things. That it posted as a purchase, not a cash advance. And that the card paid its recurring-bill rate, not its base rate. If either fails, go back to Interac and keep the $300.
The risks: your money sits in their wallet, and the clock is strict
- Custody. For at least three business days every month your rent sits with Neobanc Inc., a company that until recently was called Neo Fortune Financial, not with your bank and not with your landlord.
- Timing. Fund late and you lose that month's credit, and possibly the on-time payment. The terms put late fees on you.
- Reliability. Trustpilot shows 4.3 out of 5 across 115 reviews, with 11% one-star. This month's complaints are payments taking the full three days, a support chat that ended mid-problem, and an app that does not make clear when money has cleared.
- The credit is not cash. It reduces next month's rent through Neobanc. Leave the service and any unredeemed credit is worth nothing.
- The 2% tier can end. It is a promotion, and six months of it is always in Neobanc's hands.
- No games. The terms prohibit paying yourself or any account you control, and let Neobanc freeze funds and revoke credits while it investigates. This is for rent to a real landlord.
My strategy: e-Transfer, the 1% tier, ten days early
Here is what I am doing from October 22. Rent moves from Chexy to Neobanc. I fund the wallet by Interac e-Transfer on the 20th of each month for rent due on the 1st, on the 1% tier. No card touches it. That is $300 a year on my rent for a calendar reminder, against the $75 a year the best card would keep through Chexy after Scotiabank's change.
The card stays out of it for two reasons. The extra $150 is not worth a 1.5% fee and an open question about cash advances. And when I need a card to hit a welcome-bonus minimum spend, two months of rent through Chexy does that job at 1.75%, coded as a purchase, on a service that has said in writing which cards earn what.
The pick
- You pay rent by e-Transfer today: move it to Neobanc, pick the 1% tier, fund it ten days early. 1% of your rent for nothing.
- You want the 2% tier: only if you expect to stay in the same place, paying through Neobanc, for well over a year, and can wait six months for the first credit.
- You want a card in front of it: test one month and read the statement before you trust the extra half a percent.
- You are chasing a welcome bonus: use Chexy for those two months, not Neobanc.
And if a card is involved at all, pay it in full every month. Rent at 21% interest is the most expensive rent in the country.
Before you sign up: confirm the live fees and tiers on Neobanc's own site. Everything in this post is dated September 26, 2026, the day it was written, and companies change their terms whenever they like. General information, not financial advice, and no affiliate links. Full details in our Terms of Use.