The Rogers World Elite Is Changing
My $200 of Rogers cash back is worth $300 until November 18. After that, $200. Here is what is changing and what I am doing about it this week.
The Rogers Red World Elite Mastercard is the card everyone calls "3% on everything with no fee." On November 18, 2026 it stops being that. This post covers how the 3% actually worked, exactly what Rogers Bank is changing, who comes out ahead, the five things to do before the deadline, and whether the card is still worth a slot in your wallet afterwards. Start with the question most cardholders never asked: how did a 2% card ever pay 3%?
The whole post in one picture. The numbers are real and the receipts are below.
How the 3% actually worked
The card never earned 3%. It earns 2% on everything if you have any Rogers, Fido, Shaw or Comwave service, and 1.5% if you don't. The trick was at the other end. When you redeem your cash back against a Rogers purchase, the bank multiplies it by 1.5. Rogers' own example: $100 of cash back pays $150 of your Rogers bill. So a Rogers customer who earned 2% everywhere and always redeemed against the phone bill got 3% of value on every dollar spent, not just on the Rogers bill. US-dollar purchases earn 3%, so those were worth 4.5% the same way.
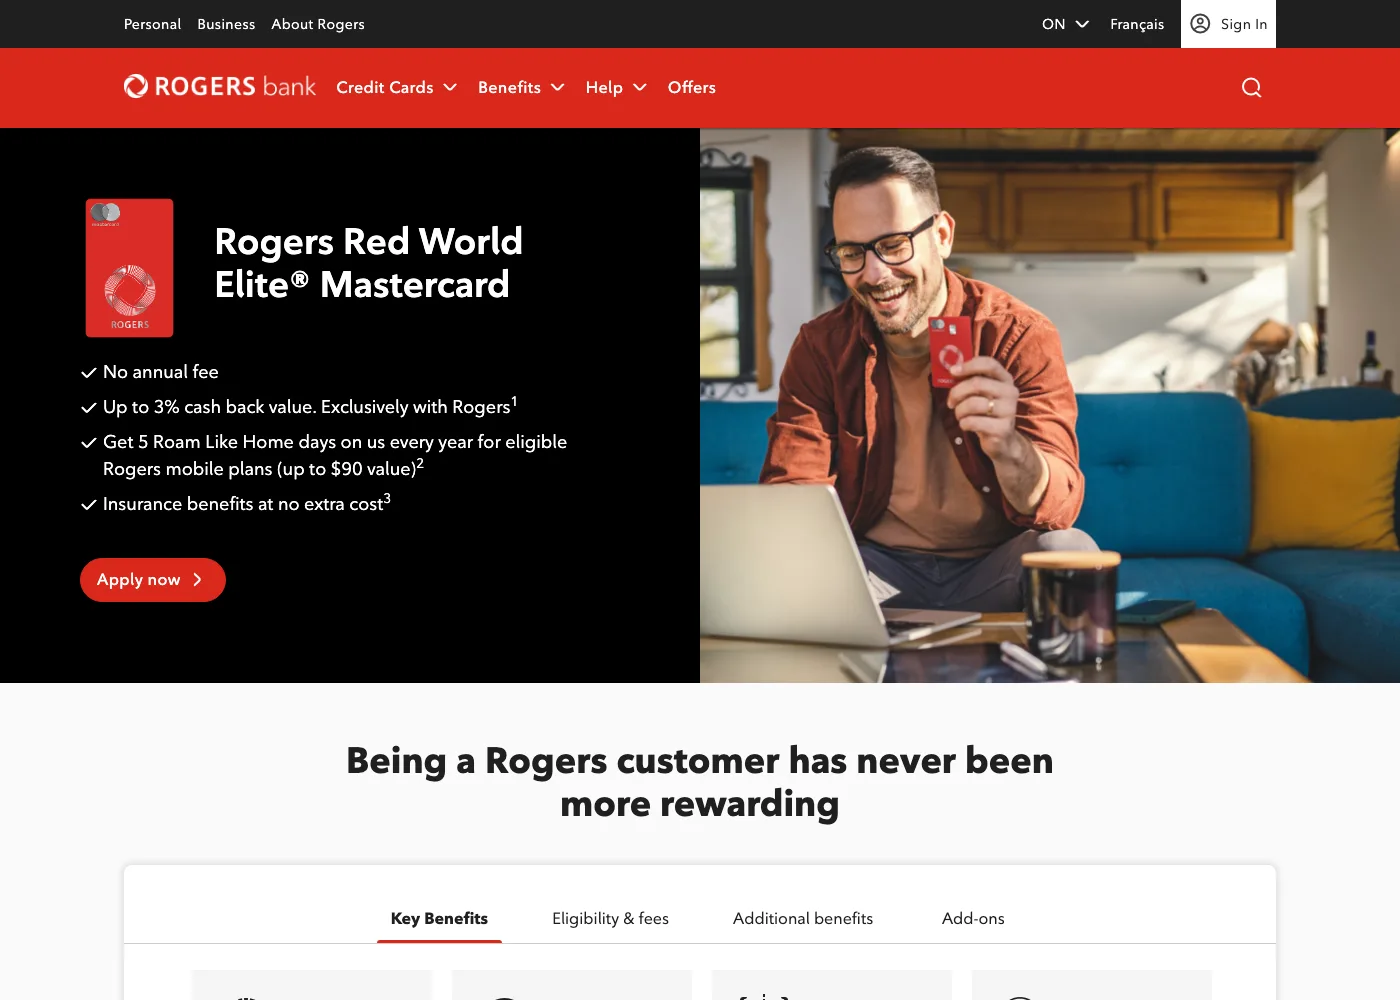
rogersbank.com, September 16, 2026. The page still says "up to 3% cash back value." Footnotes 1 and 2 carry the 1.5x redemption bonus, and further down the page a paragraph says it ends November 18.
There was always a catch, and it is the reason this card rewarded people who paid attention. Your Rogers bill is the bottleneck. The bonus only applies to cash back you redeem against Rogers purchases, and you can only redeem against a transaction posted in the last 90 days. Put $1,000 a month on the card and you earn $20, which becomes $30 of bill credit, so you need a Rogers bill of at least $30 a month to absorb it. Most cardholders I know redeem once a month against the bill and forget about it. The second most common use is Costco, which only takes Mastercard, where this was the best no-fee card in the country.
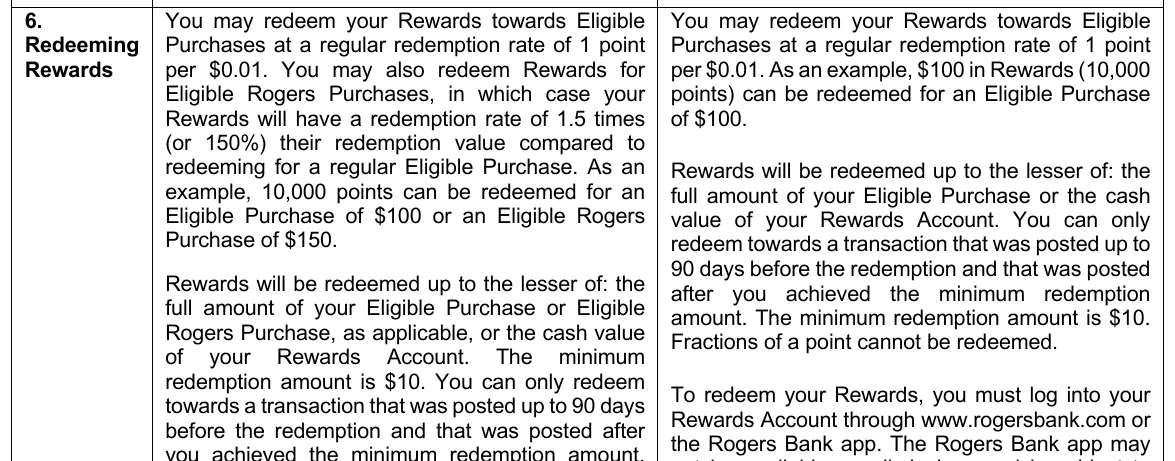
From the change notice Rogers Bank posted at rogersbank.com/legal, September 2026. Left column is today's rule, $150 of Rogers bill for 10,000 points. Right column is the rule from November 18: $100.
What changes on November 18
Rogers Bank sent every World Elite cardholder a notice in August. There are five separate Rogers cards now (Red, Red World, Red World Elite, Red World Elite Business and Red World Legend), each with its own notice and its own numbers. Everything below is from the World Elite notice, the card I hold.
| Today | From November 18, 2026 | |
|---|---|---|
| Everyday spending | 2% (1.5% with no Rogers service), 3% in US dollars | Unchanged |
| Redeeming against a Rogers bill | 1.5x: $100 of cash back pays $150 | 1x: $100 pays $100 |
| Earning on Rogers bills and rogers.com purchases | 2%, then 1.5x at redemption | 5%, inside the same $61,000 yearly cap |
| Trip cancellation, interruption and delay insurance | Included | Removed |
| Emergency medical, under 65 | 10 days per trip | 15 days per trip |
| 5 Roam Like Home days (up to $90) | Included | $75 roaming credit a year, from January 12, 2027 |
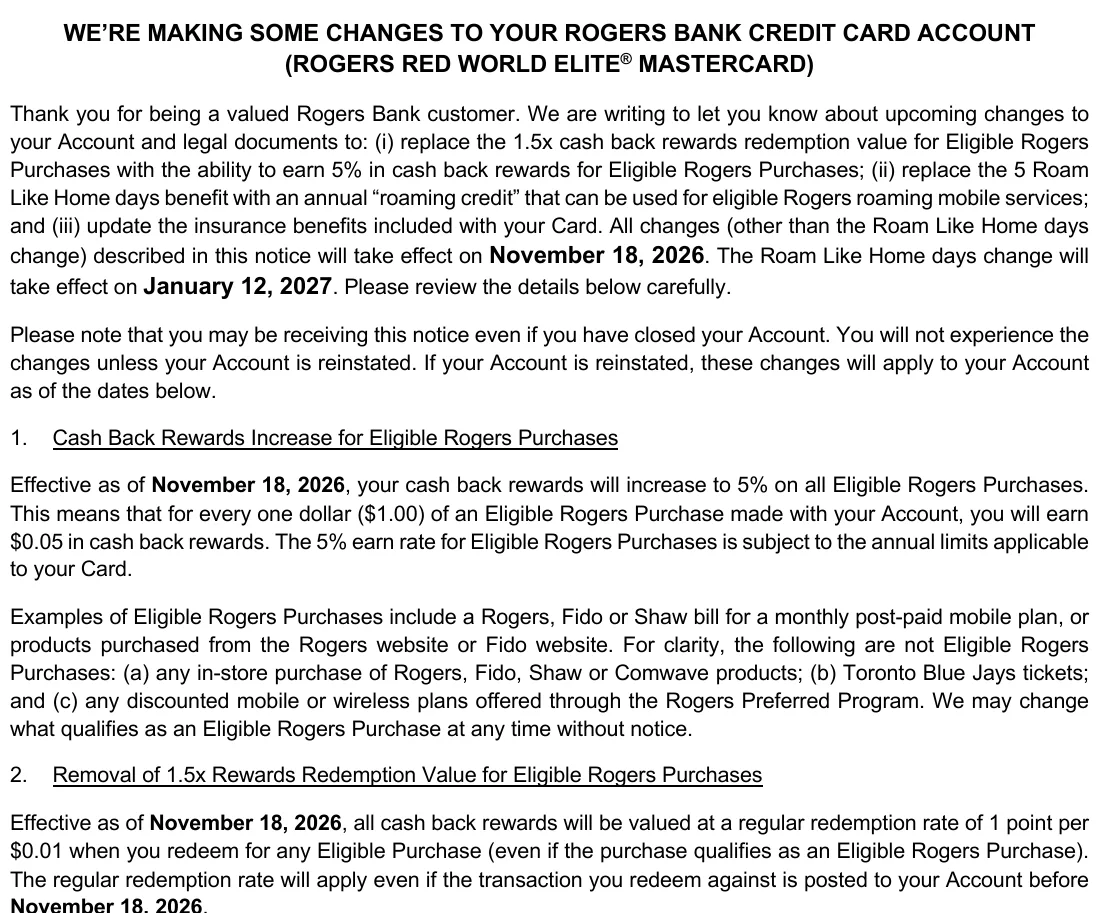
The official notice, rogersbank.com/legal, September 2026. Section 2 is the one that matters: the regular rate "will apply even if the transaction you redeem against is posted to your Account before November 18, 2026." The redemption has to happen before that date, not the purchase.
Three details in the fine print that the headline skips:
- "Eligible Rogers Purchase" got narrower. Today it includes purchases at participating Rogers and Fido stores. From November 18 it means bill payments not made in-store, online orders from rogers.com or fido.ca, The Shopping Channel, direct subscriptions to Sportsnet+, CityTV+ or Discovery+, and the Jays Shop at Rogers Centre. In-store purchases and Blue Jays tickets are out.
- Discounted plans through the Rogers Preferred Program do not count. If your phone plan comes through your employer's corporate discount, your bill earns 2%, not 5%. A lot of people are on those plans without knowing the name.
- The insurance cut is real money. I used the trip interruption coverage once and it paid me back a couple hundred dollars. From November 18 that coverage is gone, along with trip cancellation and trip delay. If you book and charge a trip before November 18, the old coverage still applies to it.
Who wins and who loses
The old value was simple: 3% of everything you spend, as long as your Rogers bill could absorb it. The new value is 2% of everything plus 5% of your Rogers bill. Put those side by side and you get one rule: you only come out ahead if your non-Rogers spending is less than twice your Rogers bill. Almost nobody is in that position.
- $1,000 a month on the card, $100 a month Rogers bill. Today: $396 a year. After: $300. You lose $96 a year.
- $2,000 a month on the card, $100 a month Rogers bill. Today: $756. After: $540. You lose $216 a year.
- $500 a month on the card, $250 a month Rogers bill. Today: $270. After: $270. Break-even. This is the family with three phone lines, internet and TV all on one Rogers account who barely use the card for anything else.
That is the trap in the "up to 5%" headline. Five is bigger than three, so it reads like a raise. It is a raise on the smallest slice of your spending and a cut on all the rest. Same trick I wrote about in Churning 101: read the footnote, not the slogan.
What I am doing before November 18
- Redeem the entire balance against my Rogers bill, this week. The notice is explicit that a redemption made on or after November 18 pays 1x, even against an older bill. My $200 becomes $300 of bill credit now, or $200 in December. Redemptions have to be made in the Rogers Bank app, $10 minimum, against a Rogers transaction posted in the last 90 days, so anything from mid-August onward is fair game.
- If the balance is bigger than three months of bills can absorb, buy something I already need online at rogers.com or fido.ca before November 18 and redeem against that at 1.5x. A phone, a case, a charger. Do not buy junk to chase a bonus. That is how the bank wins.
- Book any trip I want cancellation or interruption coverage on before November 18 and charge it to this card. After that date the card offers none, so the next trip gets booked on a card that does.
- Use the Roam Like Home days before January 12, 2027. Unused days are deleted that day and replaced with the $75 credit.
- Stop treating the card as a 3% card. From November 18 it is a 2% card with a 5% phone bill. That still has a place, which is the next section.
And, as always: pay the card in full every month. At 21.99% interest one carried balance wipes out years of this optimization.
The card after November 18
Here is the honest verdict. For a Rogers customer, this becomes a no-fee, flat 2% Mastercard with 5% on the phone and internet bill and a small edge on US-dollar spending (3% back against a 2.5% conversion fee). That is a worse card than it was. It is still one of the best no-fee cards in the country, because the competition got worse at the same time:
- The Wealthsimple Visa Infinite, the card everyone on Reddit says they are switching to, pays new cardholders 1% since April 2026, and charges $20 a month unless you keep $100,000 with Wealthsimple or move your paycheque there.
- The RBC Cash Back Mastercard cuts everything outside groceries to 0.5% on October 1, 2026.
- The Tangerine Money-Back pays 2% only in the two or three categories you pick, and 0.5% on the rest.
- The SimplyCash from American Express pays 2% on gas and groceries and 1.25% elsewhere, and Costco does not take it.
- The CIBC Costco Mastercard pays 1% inside the warehouse.
So the Rogers card keeps its job as the Costco card and the no-fee everything-else card. It just stops being special. If you do not have a Rogers, Fido, Shaw or Comwave service, it is a 1.5% card and you can do better.
Where it sits in a churner's wallet
This was never a churning card and it still is not. There is no welcome bonus on the official page today, the income floor is $80,000, and the value was always in holding it, not opening it. In the language of Churning 101, it is a keeper: the no-fee card you leave open for years while the welcome-bonus cards rotate through. It stays in my wallet for Costco and the phone bill. It leaves the front pocket.
The exact math on the three churning cards from the first post is next. Until then, open the Rogers Bank app and redeem.
Before you apply: confirm the live terms on the bank's own page. Everything in this post is dated September 16, 2026, the day it was written, and banks change their offers whenever they like. General information, not financial advice, and no affiliate links. Full details in our Terms of Use.