4% on Rent Ends Next Month. Now What?
My rent is about $2,500 a month. Today I pay it through Chexy on the Scotia Momentum Visa Infinite+, and it pays me $675 a year. Scotiabank is changing its rules, and after October 21 this stops working. Here is what to do, and how to keep $300 a year of it without a credit card.
Rent is the biggest payment most of us make every month, and for most of my life it earned nothing. Then a service let me put it on a credit card, the Scotia Momentum paid 4% on it, and after the service's fee I kept 2.25%. Rent became my best-paying expense. Scotiabank is ending that. What follows is the change, the date that matters, the cards that still count rent as a bill, and the one switch most people have not thought of: the service you pay through.
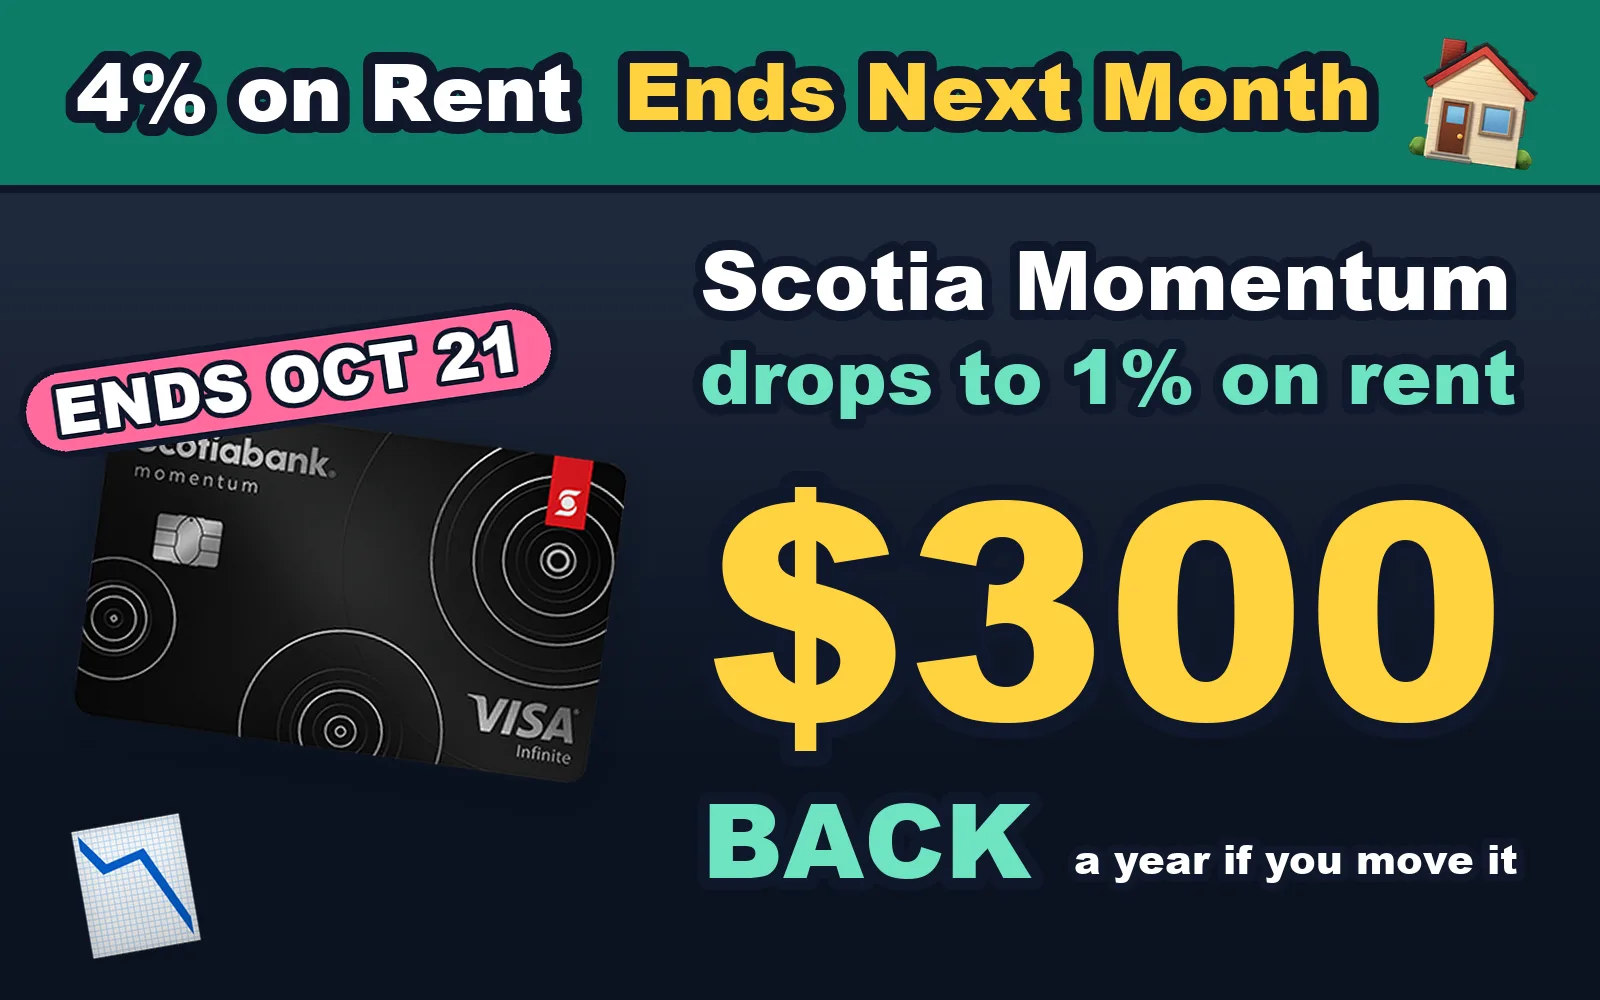
The whole post in one picture. The numbers are real and the receipts are below.
On October 22, rent on the Scotia Momentum drops from 4% to 1%
The Scotia Momentum Visa Infinite+ pays 4% on recurring bills. Rent paid through a service like Chexy is billed as a recurring payment, so it earned 4%. From October 22, 2026, Scotiabank excludes two merchant codes from that category: rent (code 6513) and tax payments (code 9311). Rent and taxes fall to the card's regular 1%. Property tax, condo fees and CRA payments go with it.
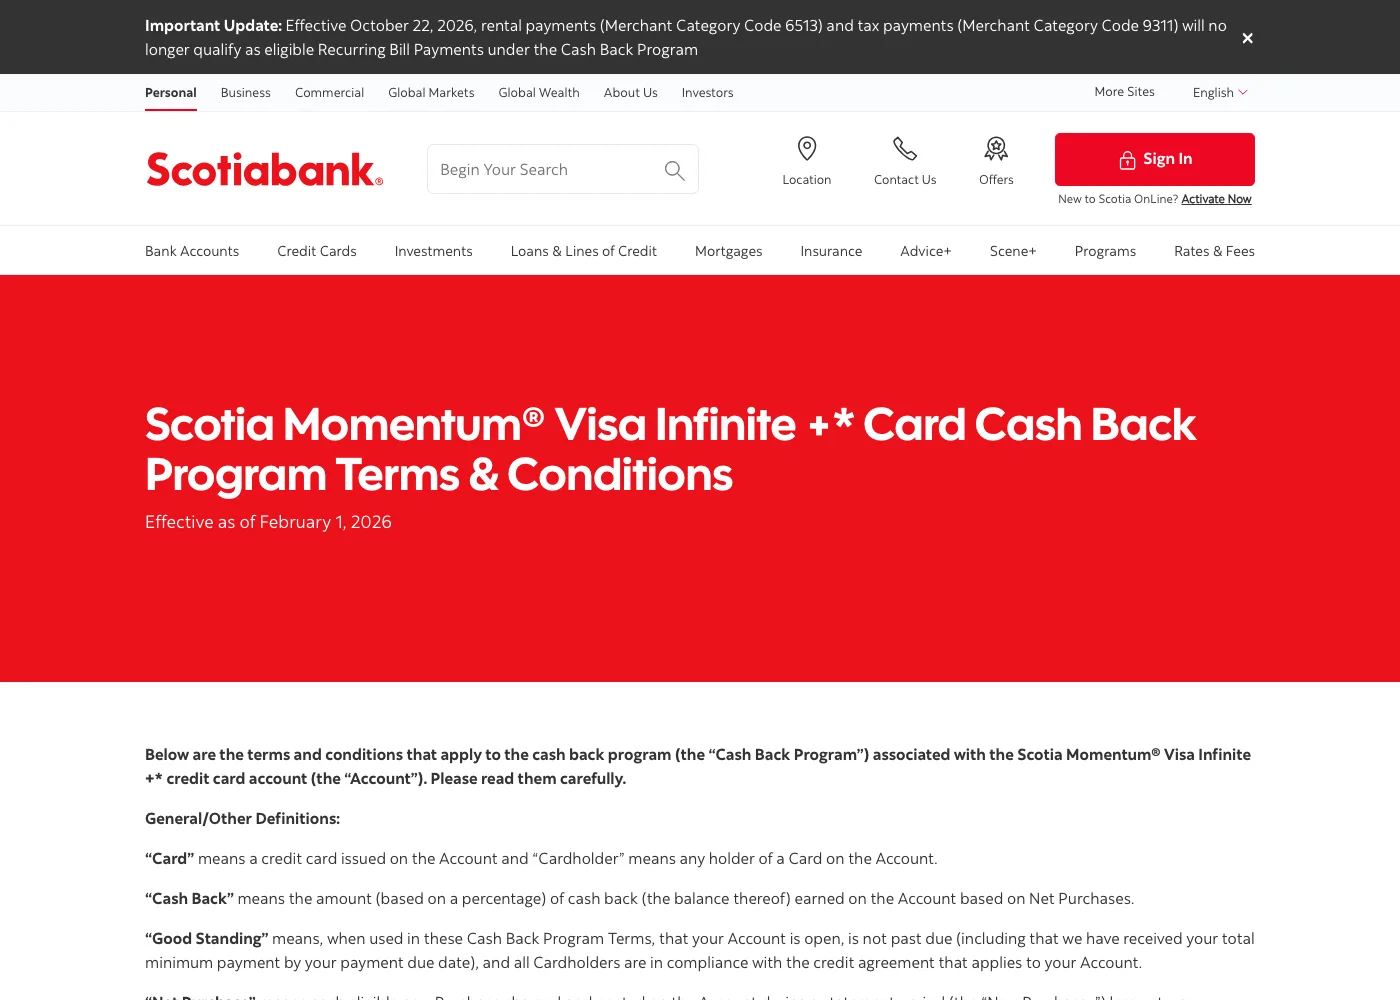
scotiabank.com, September 26, 2026. The banner at the top of the cash back terms is the whole change in one sentence. Two merchant codes, one date.
Everything else in the category stays at 4%: utilities, phone and internet, insurance, car lease, daycare, tuition, gym, subscriptions. Groceries stay at 4% too. The card is not getting worse for anyone except people paying rent or taxes with it, which is exactly who this post is for.
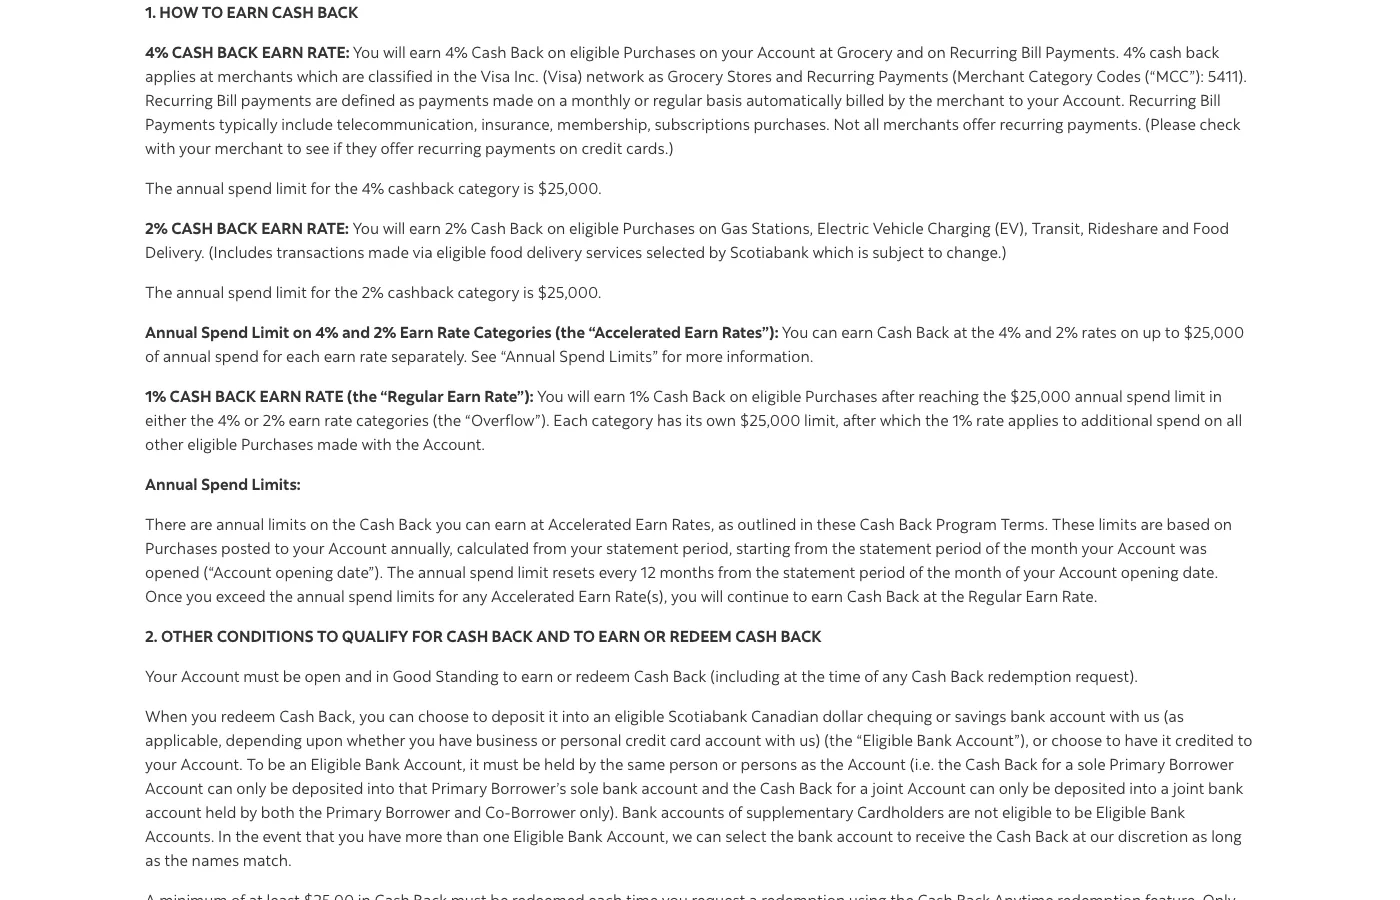
scotiabank.com, September 26, 2026. The definition of a recurring bill has not changed. Rent still fits it. Scotiabank simply carved two merchant codes out.
Same rent, same card: $675 a year becomes a $225 loss
The 4% was never 4% in my pocket. My rent is $2,500 a month, paid through Chexy, which charges 1.75% to put it on a card. On the Scotia Momentum the year looked like this:
- Cash back at 4% on $30,000: $1,200
- Chexy fees at 1.75%: $525
- Net: $675 a year, on money that used to earn nothing.
From October 22 the same setup pays 1%, which is $300, against the same $525 of fees. Net: $225 a year lost. That is a $900 swing, and it does not shrink, it goes negative. Anyone who leaves their rent on this card after October 22 is paying Chexy for the privilege of losing money.
chexy.co, September 26, 2026. Chexy published the change the day Scotiabank announced it and built a switch tool for affected payments. The date that matters is the charge date.
Charge October's rent by October 21
The rule is the charge date, not the due date. A payment charged to the card on October 21 earns 4%. The same payment charged October 22 earns 1%, even if it is for October's rent. So if your service lets you pick the date the card is charged, charge the last payment on or before October 21. Chexy schedules the card switch for October 22 automatically if you use its tool.
Other cards still count rent as a bill, but the fee eats most of it
Scotiabank carved rent out by merchant code. The other banks did not. Chexy's own notice names four cards that keep paying their recurring-bill rate on rent through it:
- The Tangerine Money-Back World Mastercard, or the no-fee Money-Back card with no income requirement, pays 2% on recurring bills with no cap and no annual fee, if you pick Recurring Bill Payments as one of your categories.
- The TD Cash Back Visa Infinite pays 3% on recurring bills, up to $15,000 a year, then 1%, for $139 a year, rebated in year one.
- The CIBC Dividend Visa Infinite pays 2% for $120 a year, and the Rogers Red World Elite pays 2% on everything for free, 3% until November 17 if you redeem against a Rogers bill.
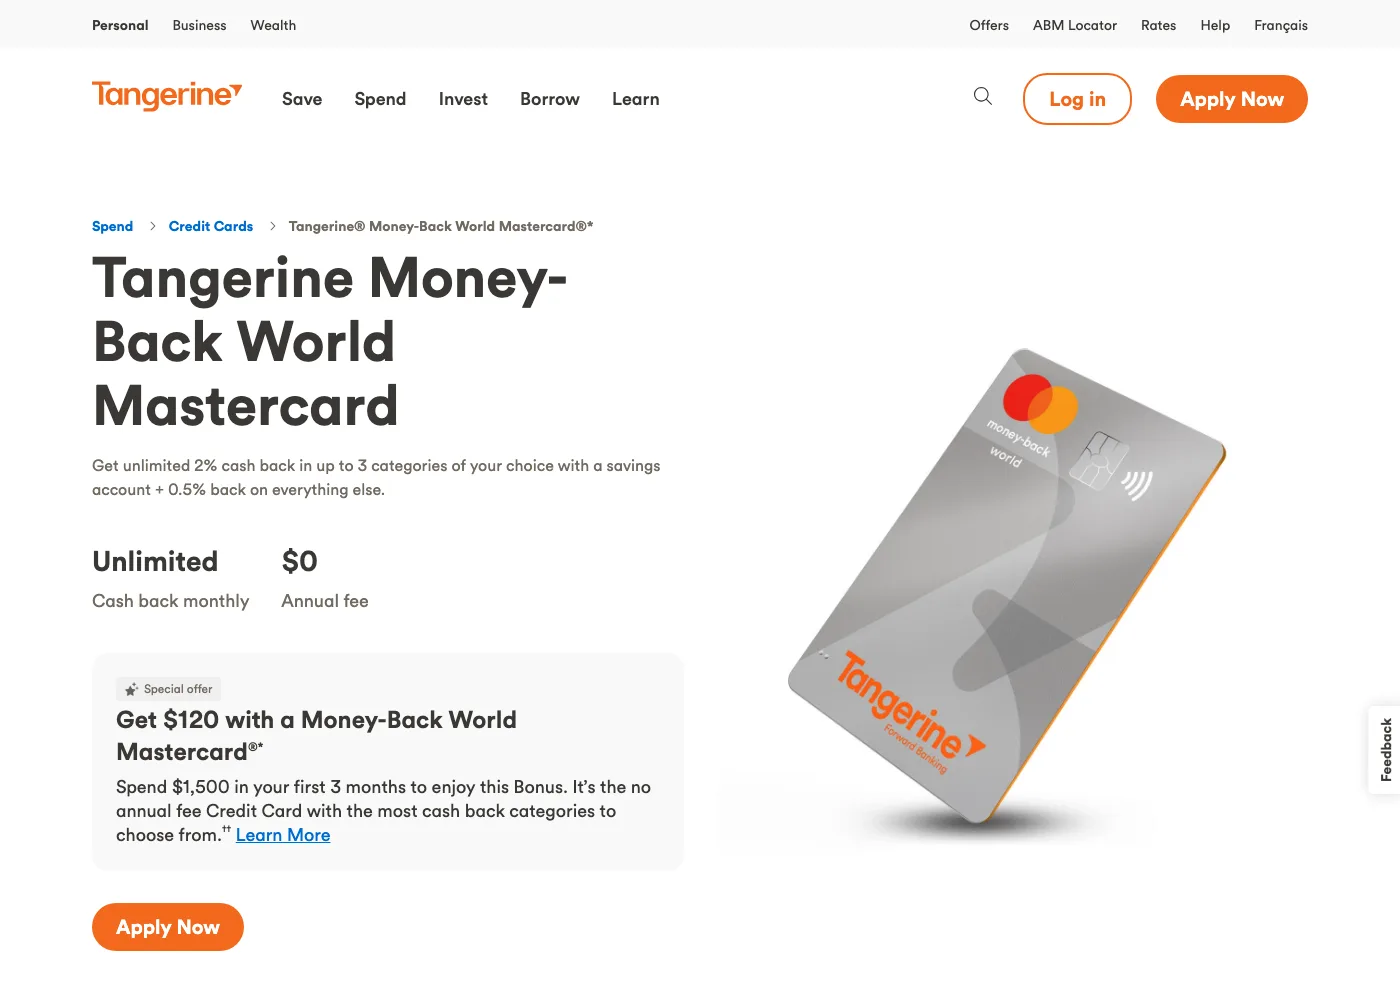
tangerine.ca, September 26, 2026. Pick Recurring Bill Payments as one of the three categories and rent through Chexy earns the 2%. No cap, no fee.
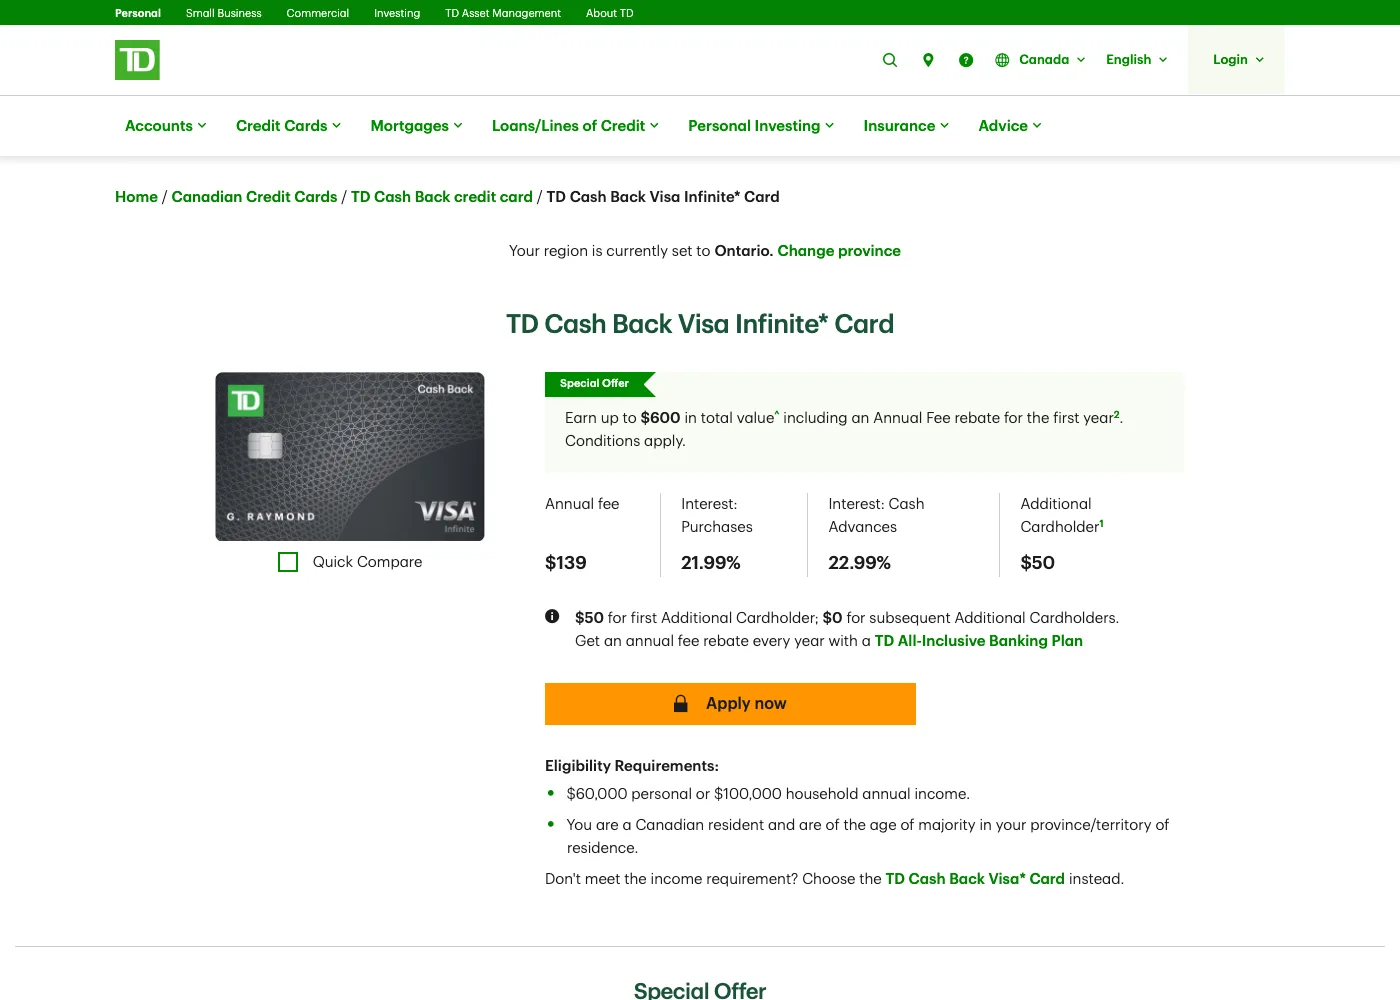
td.com, September 26, 2026. 3% on recurring bills, but only on the first $15,000 a year. Two months of rent clears the welcome bonus.
Now put the fee back in. Against Chexy's 1.75%, a 2% card keeps 0.25%. On my rent that is $75 a year. The TD card's 3% runs out at $15,000, so on $30,000 of rent it earns exactly what Tangerine earns, $600, and then charges $139 for it. Rent on a card through Chexy is no longer a strategy. It is a rounding error.
| Card on the rent | Earns on rent | Net a year through Chexy at 1.75% |
|---|---|---|
| Scotia Momentum Visa Infinite+, before October 22 | 4% | +$675 |
| Scotia Momentum Visa Infinite+, from October 22 | 1% | −$225 |
| Tangerine Money-Back, no fee | 2% | +$75 |
| TD Cash Back Visa Infinite, $139 after year one | 3% on the first $15,000 | +$75 |
| Rogers Red World Elite, no fee | 2% | +$75 |
| No card. Neobanc by e-Transfer | 1% credit, no fee | +$300 |
All figures on $2,500 a month, before annual fees.
The service you pay through matters more than the card
The last row is the answer. Neobanc, a rent service like Chexy, pays its own 1% credit on rent even when you fund it by Interac e-Transfer, with no fee and no card. On $30,000 of rent that is $300 a year, four times what the best card keeps through Chexy, and nothing can be coded as a cash advance because there is no card. Putting a 2% card in front of it costs 1.5% and adds only $150 more, with a question mark over how the charge posts. I wrote up how Neobanc works, the tiers, the fees and the risks separately, because it deserves its own fine print. The short version: it is a prepaid wallet, you fund it three business days early, and the credit is spendable only on rent.
Keep the Scotia card for groceries and the other bills
Do not cancel the Momentum over this. It still pays 4% on groceries and on every recurring bill that is not rent or tax, up to $25,000 a year in each category, which is the best rate in the country for phone, internet, insurance, daycare and subscriptions. Move the rent off it and leave the rest where it is.
The best use of rent by card was never the 4%
The most a card ever paid me on rent was $675 a year. A welcome bonus pays more in one month. The CIBC Aeroplan Visa Infinite from Churning 101 asks for $3,000 of spending in 90 days for up to 50,000 points, about $1,000 in flights. Two months of my rent is $5,000. The fee on that is $88 through Chexy, and the card has no idea the money was rent. Rent is the cleanest way I know to hit a minimum spend without buying anything.
That does not change on October 22. It works with every card that has a bonus, and it works for taxes too. Paying the CRA with a card at 1% minus a fee is a loss. Paying the CRA with a card that owes you a welcome bonus is the cheapest bonus you will ever earn.
The pick
- Rent on the Scotia Momentum today: charge your last payment by October 21. Then move the rent to Neobanc and fund it by e-Transfer on the 1% tier, ten days before it is due. No card, no fee, $300 a year on my rent. Keep the Scotia card for groceries and every other bill.
- Want a card in the mix anyway: a Tangerine Money-Back card through Neobanc adds about $150 a year for a 1.5% fee. Run one month first and check how it posts before you commit. The Chexy route with any card is $75 a year and not worth the setup.
- Opening a card for a welcome bonus: put two months of rent on it through Chexy, pay the fee, collect the bonus, then move the rent back.
And if a card is anywhere in this, pay it in full every month. A rent payment at 21% interest wipes out every dollar above in a single statement.
Before you apply: confirm the live terms on the bank's own page. Everything in this post is dated September 26, 2026, the day it was written, and banks change their offers whenever they like. General information, not financial advice, and no affiliate links. Full details in our Terms of Use.